
The State of Lime in India, 2026
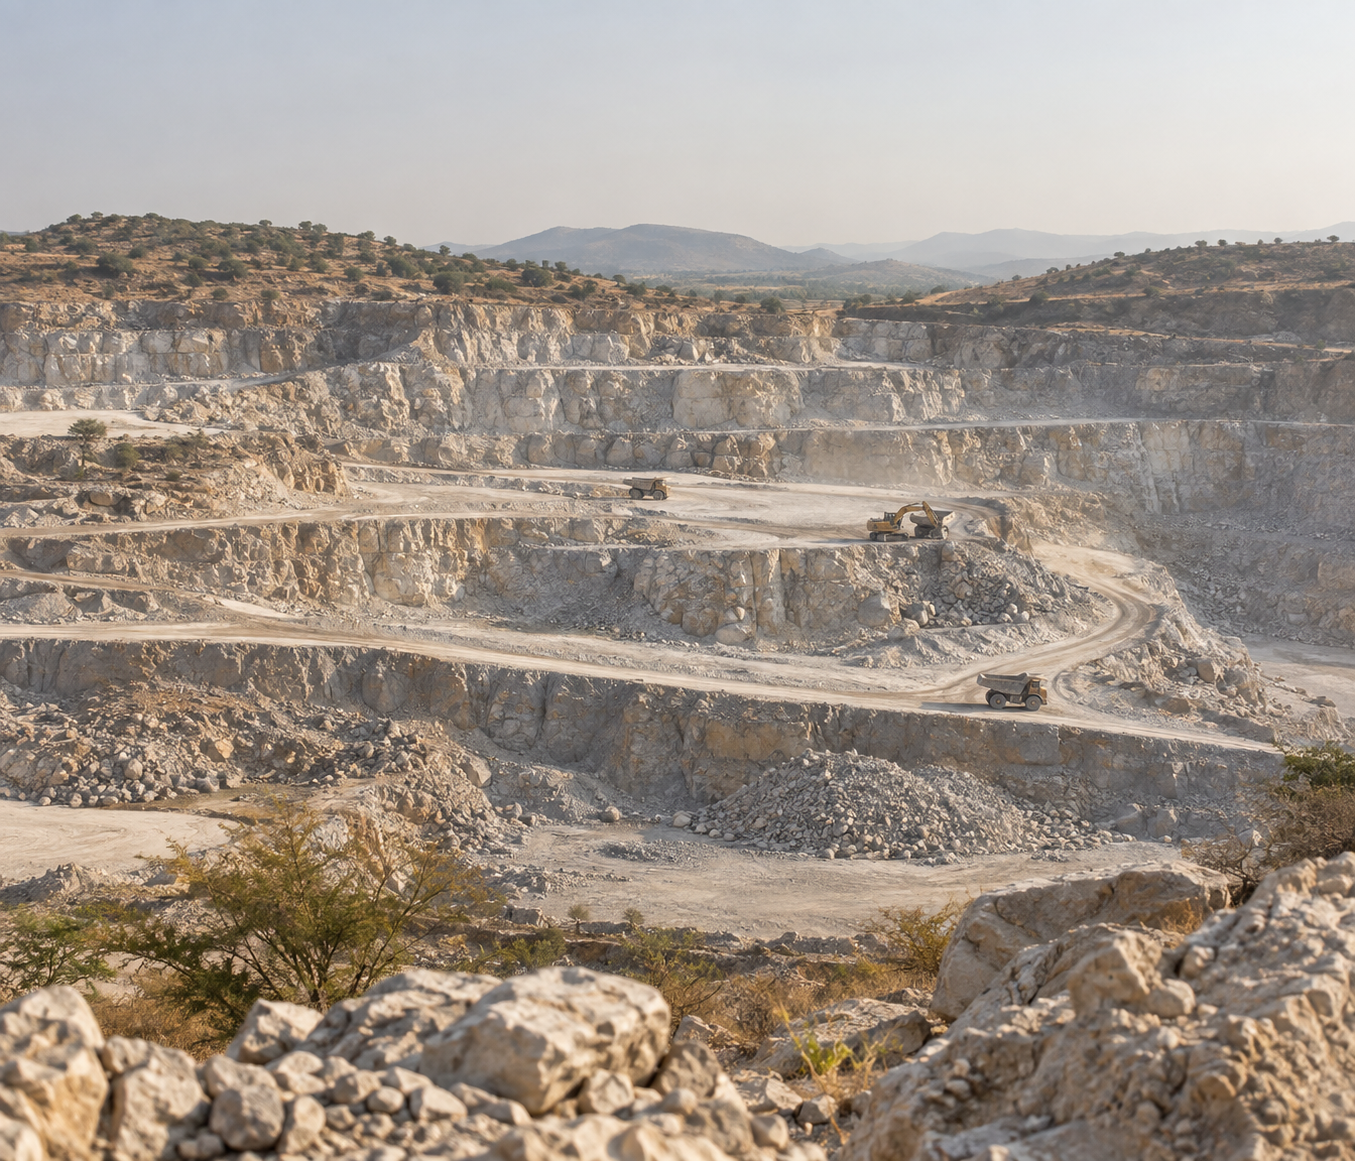

India makes more lime than any country except China, and produces 484 million tonnes of limestone a year. So why did it import 34 million tonnes of limestone and nearly a million tonnes of quicklime in 2025? This annual report sets out India's lime economy: production, demand, trade, freight, supply and policy, with a year on every number.
Search for "India lime market" and one of the first numbers you will meet is USD 4.65 billion. It comes from a well-known research house, it is widely quoted, and it describes a citrus fruit.
That is a fair summary of how well India understands its own lime economy. The country makes more lime than any nation except China. Lime goes into the steel India is building its infrastructure with, the water it is piping to villages and the sugar on its tables. Yet there is no official statistic for how much lime India makes, and the public numbers that do exist rarely agree.
India is the world's second-largest lime producer, at an estimated 17 million tonnes a year, behind only China. Steel is by far the largest user, followed by water treatment, chemicals, sugar and construction. Yet India imported about 0.94 million tonnes of quicklime and 34 million tonnes of limestone in 2025, mostly from the UAE and Oman.
This report pulls together what can be sourced: production, demand, trade, freight, supply and policy, with a year on every number. It will be updated each year.
Key figures at a glance
Every figure below carries the year it refers to. Two are our own estimates, and they are labelled.
| Indicator | Figure | Year | Source |
|---|---|---|---|
| Lime output | About 17 Mt, second in the world | 2024 and 2025 (estimate) | USGS |
| Limestone output | 484 Mt, second in the world | FY2025-26 | Ministry of Mines (PIB) |
| Crude steel output | 168.42 Mt | FY2025-26 (provisional) | Joint Plant Committee |
| Lime used by steelmaking | About 8 to 13 Mt | FY2025-26 | Dr. Lime estimate |
| Limestone imports | 34.2 Mt, 78% from the UAE | 2025 | UN Comtrade |
| Quicklime imports | 0.94 Mt, from the UAE and Oman | 2025 | UN Comtrade |
| Dolomite imports | 6.46 Mt | 2025 | UN Comtrade |
| Limestone exports | About 6.5 Mt, mostly to Bangladesh | 2025 | UN Comtrade |
| Coal power units with FGD completed | 49 units, 25.6 GW | March 2025 | Ministry of Power |
| Lime steel would need at 255 Mt output | About 13 to 19 Mt | 2030-31 scenario | Dr. Lime estimate |
The numbers nobody agrees on
First, a definition, because it matters more than usual here. In this report, "lime" means quicklime and hydrated lime: the materials made by burning limestone, and by then adding water. We also follow the high-purity limestone that feeds them, and that specification-driven industries such as glass and flue gas treatment buy directly. Where an industry uses limestone rather than lime, we say so.
With that settled, the measurement problem becomes clear.
India has no official lime statistic. The Indian Bureau of Mines tracks limestone in detail, but lime is a manufactured product, made in kilns large and small across the country, and no agency counts it. The best available volume figure comes from the United States Geological Survey, which puts India's lime output at about 17 million tonnes. The same figure appears for both 2024 and 2025, which tells you it is a rounded estimate rather than a measurement.
Commercial research fills the gap with value estimates. Read the table below with one question in mind: which lime is being measured?
| Source | What it measures | Figure | Year | Caveat |
|---|---|---|---|---|
| USGS | Lime output | About 17 Mt | 2024 and 2025 (estimate) | Rounded estimate |
| IMARC | Lime market value | USD 1.62 bn | 2025 | Commercial estimate |
| Intel Market Research | Quicklime market value | USD 2.34 bn | 2024 | Commercial estimate |
| Mordor Intelligence | "India Lime Market" | USD 4.65 bn | 2025 | Covers the citrus fruit |
| Ministry of Mines (PIB) | Limestone output | 484 Mt | FY2025-26 | Official figure |
The two estimates for the mineral differ by about 1.5 times. The largest number is not about the mineral at all.
Before anyone sizes India's lime market, they need to be sure they are measuring the right lime.
Where India's lime goes
One industry dominates the answer: steel.
Lime is the flux that makes steelmaking work. It forms the slag that pulls silica, phosphorus and sulphur out of molten iron. A basic oxygen furnace uses around 75 kg of lime for every tonne of steel. An electric arc furnace uses less, typically 25 to 60 kg, according to the US National Lime Association. That is why lime materials for steel and metallurgy are held to such tight limits on reactivity and sulphur.
India produced 168.42 million tonnes of crude steel in FY2025-26, according to provisional Joint Plant Committee data. At a blended 50 to 75 kg per tonne, steelmaking alone accounts for roughly 8 to 13 million tonnes of lime a year. That is our estimate, but even its lower end makes steel the largest lime user in the country by a wide margin.
The rest of India's lime is spread across industries that each use less, but often need more precise material.
| Sector | What lime does | 2026 demand signal |
|---|---|---|
| Steel | Flux; forms slag that removes silica, phosphorus and sulphur | 168.42 Mt crude steel (FY2025-26, provisional) |
| Water | pH correction, softening, purification | Jal Jeevan Mission 2.0: Rs 8.69 lakh crore, running to December 2028 |
| Sugar | Clarifies cane juice before crystallisation | About 324 lakh tonnes gross sugar (2025-26 season, ISMA estimate); roughly 1.4 to 2.0 kg of lime per tonne of cane in sulphitation mills |
| Chemicals | Calcium carbide, bleaching powder, calcium salts | A calcium carbide complex in Gujarat with about 5,000 tonnes a day of new quicklime kilns under construction |
| Construction | AAC blocks, mortar, plaster, soil stabilisation | No reliable public data |
Water treatment is the steadiest of these. It is tied to public programmes with fixed timelines rather than to commodity cycles, which is why lime for water treatment is one of the more predictable parts of demand.
Construction is the hardest to measure. Lime goes into AAC blocks, mortar, plaster and road soil stabilisation, but no reliable public data tracks how much.
Glass and flue gas treatment are missing from the table on purpose. Both are major buyers of calcium, but they buy it as limestone, as our analysis of India's growing glass industry explains. Their story belongs to the next section, which is where India's lime economy gets interesting.
Plenty of limestone, in the wrong grade and the wrong place
India is not short of limestone. It produced 484 million tonnes in FY2025-26, the second-largest output in the world, according to the Ministry of Mines. Its total resources run to about 227,589 million tonnes.
So it is surprising to find that India is also one of the world's largest limestone importers. In calendar 2025 it imported 34.2 million tonnes, 78% of it from the UAE and 18% from Oman, according to UN Comtrade data. It also imported 0.94 million tonnes of quicklime from the same two countries.
Two things explain it: grade and place.
Grade
Most Indian limestone is made for cement. In the Indian Bureau of Mines' latest limestone chapter, from the Indian Minerals Yearbook 2022, 69% of resources are cement grade. The blast-furnace and steel-melting-shop grades that steelmakers need make up about 9%, and chemical grade about 2.4%. On the output side, 97% of the limestone India extracts is cement grade.
Cement is forgiving. It tolerates silica, iron and magnesium that a steel converter or a chemical reactor would reject. The specification gap between the two is set out in what high-purity limestone means in numbers.
Place
Steel-grade stone does exist in India. One recent analysis puts steel-melting-shop grade reserves in Jaisalmer alone at about 1,750 million tonnes. Yet India produced only about 8.9 million tonnes of steel-grade limestone in 2023-24.
The reason is distance. Much of India's high-grade stone sits in western Rajasthan. Most of its steel is made in the east and on the coasts. Moving limestone 1,853 km by rail from Jaisalmer to Bokaro costs about Rs 2,600 a tonne, which makes the delivered domestic price higher than imported stone at about Rs 3,362 a tonne, according to the same analysis. A coastal plant, meanwhile, pays almost nothing to move stone from port to furnace.
The trade data shows the pattern clearly.
| Material (HS code) | Imports, 2025 | Main sources | Exports, 2025 | Import unit value |
|---|---|---|---|---|
| Limestone (2521) | 34.2 Mt | UAE 78%, Oman 18% | About 6.5 Mt, mostly to Bangladesh | About USD 21 a tonne |
| Quicklime (252210) | 0.94 Mt | UAE 527 kt, Oman 374 kt | About 0.13 Mt of lime, mostly to Nepal | About USD 112 a tonne (all lime) |
| Dolomite (2518) | 6.46 Mt | Bhutan, UAE, Oman | Not significant | Not calculated |
| Calcium carbonate, including PCC (283650) | 540 kt | Egypt, Vietnam | Not significant | About USD 101 a tonne |
Read the export column against the import column. India sends cement-grade stone to Bangladesh and buys steel-grade stone and lime from the Gulf. The unit values tell the same story from another angle. Imported limestone averaged about USD 21 a tonne in 2025, while imported lime averaged about USD 112. The value is in the processing, and India is buying a share of it abroad.
The map is starting to shift. The Western Dedicated Freight Corridor has made Rajasthan stone easier to move, and the same analysis reports limestone output growing about 19% in Nagaur district against about 10% across the state.
How India makes its lime
India's lime comes from three very different kinds of kiln.
The first is the merchant cluster. Jodhpur in Rajasthan and Katni in Madhya Pradesh, long called the city of lime, are the best known. Jodhpur's cluster was last studied in detail in 2011, when it had about 100 units of 15 to 75 tonnes a day, mostly vertical shaft kilns fired on pet coke. They used about 6.4 to 6.9 GJ of fuel per tonne of quicklime, against a theoretical need of about 3.8 GJ. Katni has about 150 small units. These clusters serve construction and general industry well, but few publish the chemistry and consistency data that specification-driven buyers need.
The second is the captive kiln. Integrated steel plants burn their own lime next to the furnace, increasingly in high-efficiency parallel-flow regenerative kilns. A large share of India's lime is likely made this way, though no public source splits captive output from merchant output.
The third is new and large. A calcium carbide complex under construction in Gujarat has ordered six kilns with a combined capacity of about 5,000 tonnes of quicklime a day, described by their maker as the largest greenfield lime plant ever built.
Fuel ties all three together. Energy is the largest cost in making lime, and pet coke is the dominant fuel. When the Supreme Court restricted imported pet coke in July 2018, lime kilns were one of only four industries allowed to keep using it, alongside cement, calcium carbide and gasification. Kiln efficiency therefore sets both the price of Indian lime and its emissions. Lime is not a covered sector under India's Carbon Credit Trading Scheme, though captive kilns fall inside the steel sector's boundary.
Foreign supply, meanwhile, is moving closer. None of the global lime majors operates a kiln in India. But in January 2026, one of them bought a lime plant in Oman that it says serves markets from India to Korea. Oman is already India's second-largest source of imported quicklime.
India has plenty of lime capacity. What it has less of is consistent, specification-grade lime, made close to where it is used.
Policy is moving demand, not always in one direction
Several policies shape Indian lime and limestone demand, and they do not all push the same way. The table sets out what changed and what it means.
| Policy | What changed | What it means for lime and limestone |
|---|---|---|
| SO2 norms for coal power plants | Revised 11 July 2025. Category A plants must comply by 31 December 2027; Category B by 31 December 2028 or seek case-by-case exemption; Category C, about three-quarters of the fleet, exempt | Limestone demand for FGD falls well below the pre-2025 estimate of 7 to 10 Mt a year |
| National Steel Policy | 2017 policy: 300 Mt capacity by 2030-31. Draft new policy announced 29 September 2026: over 600 Mt capacity by 2047 | Steel remains the main engine of lime demand |
| MMDR Act, captive leases | Captive leases granted before 2015 run to 31 March 2030, then go to auction, with a right of first refusal for the existing holder | Steelmakers' long-term limestone sources come up for review |
| Jal Jeevan Mission 2.0 | Approved March 2026; Rs 8.69 lakh crore; runs to December 2028 | Steady demand for water-treatment lime |
| Critical minerals list | 30 minerals named in 2023; lime and limestone not included | No special policy support for high-purity limestone |
| BIS standards | IS 1540 covers lime for chemical industries and IS 997 covers limestone for glass; no quality control order applies to lime | Quality is still set buyer by buyer |
The flue gas story shows how quickly demand can move. For years, India's 2015 emission norms were expected to require flue gas desulphurisation across the coal fleet, and a 2020 estimate put the limestone that would take at 7 to 10 million tonnes a year. By March 2025, FGD was complete on just 49 units with 25.6 GW of capacity. The July 2025 rules then exempted about three-quarters of the fleet. FGD limestone demand will still grow, from Category A and B plants, but well below the old estimate.
Steel points the other way. On 29 September 2026, the Steel Secretary said a draft new National Steel Policy would be released within a week, targeting more than 600 million tonnes of capacity by 2047. That is roughly three times today's level.
The absence of lime and limestone from the critical minerals list is a gap we examined in the critical mineral that isn't on the list. The net effect of all this policy favours users that need high-specification material: steel, water, chemicals and glass.
What to watch in 2027
One calculation frames the decade ahead. If Indian steel reaches the 255 million tonnes of production the 2017 policy targets for 2030-31, steelmaking alone would need about 13 to 19 million tonnes of lime a year at today's usage rates. That is more than India's entire estimated lime output today. It is a scenario, not a forecast, but it shows the scale of what is coming.
These are the signals this report will track before its next edition.
| Signal | Why it matters | When |
|---|---|---|
| Draft National Steel Policy | Sets the long-run curve for lime demand | Draft due October 2026 |
| Category A FGD deadline | First real test of the revised SO2 norms | 31 December 2027 |
| Gujarat calcium carbide start-up | Largest single new block of quicklime demand | Reported for late 2026 to FY2027-28 |
| Limestone and quicklime imports | Shows whether domestic specification-grade supply is catching up | Calendar 2026 trade data |
| Gulf shipping and insurance costs | Set the delivered price of imported stone | Ongoing, with West Asia disruption |
| Rajasthan rail and freight corridor | Sets the delivered cost of domestic stone | Ongoing |
| Captive lease auctions | Reopen steelmakers' limestone sourcing | From 31 March 2030 |
Where Dr. Lime fits
The gap this report describes is specific. India does not lack limestone or kilns. It lacks specification-grade material, produced consistently and delivered where it is needed at a competitive cost.
Dr. Lime is built around that gap. Dr. Lime controls quality from the extraction stage. Its material comes from a controlled, single-source deposit in Rajasthan's limestone belt with up to 96% calcium carbonate content, and it supplies high-purity limestone products engineered for steel, glass, FGD, feed and other specification-driven applications today.
Its roadmap follows the same chain as this report. Quicklime is in its engineering phase, to be made in Maerz kilns from 2027. Hydrated lime is in development, and precipitated calcium carbonate is in design.
If you are planning lime or high-purity limestone supply for steel, water, chemicals or glass, the Dr. Lime team can help you work through the specification.
The right lime, in the right place
India's lime story for the next decade will not be about tonnes. India already makes more lime than almost anyone, and it has the stone to make more.
The story will be about grade, place and delivered cost: how much Indian lime meets specification, and whether it can reach the plants that need it for less than stone shipped across the Arabian Sea.
The first number in an honest account of India's lime market is not USD 4.65 billion. It is 17 million tonnes of lime, and the question of how much of it is the right lime.
How we built this report
This report draws on the USGS, the Ministry of Mines, the Indian Bureau of Mines, UN Comtrade, the Joint Plant Committee, the Ministry of Power, the Ministry of Environment and published research. Trade figures are calendar years; steel and limestone output are Indian fiscal years. Two figures are our own calculations: lime used by steelmaking (at 50 to 75 kg per tonne of crude steel) and the 2030-31 scenario (the same range applied to 255 million tonnes). Unit values are import value divided by import volume. Figures will be updated in each annual edition.
FAQs
How big is India's lime market?
India produces about 17 million tonnes of lime a year, according to the USGS, making it the world's second-largest producer after China. Commercial estimates value the market at roughly USD 1.6 billion to 2.3 billion, but some widely cited "India lime market" figures describe the citrus fruit, not the mineral.
Which industry uses the most lime in India?
Steel is the largest user of lime in India. At roughly 50 to 75 kg of lime per tonne of steel and about 168 million tonnes of crude steel in FY2025-26, steelmaking likely uses 8 to 13 million tonnes of lime a year. Water treatment, chemicals, sugar and construction follow.
How much lime is used per tonne of steel?
A basic oxygen furnace typically uses around 75 kg of lime per tonne of steel, and an electric arc furnace about 25 to 60 kg, according to the US National Lime Association. Across a mixed fleet like India's, a blended range of 50 to 75 kg per tonne is a reasonable working estimate.
Does India import lime?
Yes. India imported about 0.94 million tonnes of quicklime in 2025, mainly from the UAE and Oman, according to UN Comtrade data. It also imported about 28,000 tonnes of slaked lime, mainly from China and Thailand.
Why does India import limestone, and where does it come from?
India imports limestone because of grade and freight. Almost all Indian limestone is cement grade, and much of the steel-grade stone sits in western Rajasthan, far from steel plants in the east and on the coasts. In 2025, India imported 34.2 million tonnes of limestone, 78% from the UAE and 18% from Oman.
Where is lime produced in India?
Merchant lime is produced mainly in clusters such as Jodhpur and Nagaur in Rajasthan and Katni in Madhya Pradesh, with further production in Gujarat and Andhra Pradesh. A large share of India's lime is also made in captive kilns at integrated steel plants.
Do Indian coal power plants still need FGD?
Under rules revised in July 2025, Category A plants near the National Capital Region and million-plus cities must meet SO2 limits by 31 December 2027. Category B plants must comply by 31 December 2028 or seek a case-by-case exemption, and Category C plants, about three-quarters of the fleet, are exempt from the SO2 limits.
Is limestone a critical mineral in India?
No. Neither lime nor limestone is on India's 2023 list of 30 critical minerals, even though high-purity grades are scarce and India imports tens of millions of tonnes of limestone each year.
Does Dr. Lime supply lime?
Dr. Lime supplies high-purity limestone products for steel, glass, FGD, feed and other industrial applications today. Quicklime is in its engineering phase, to be made in Maerz kilns from 2027, and hydrated lime and precipitated calcium carbonate are in development and design. Buyers can contact the Dr. Lime team for current availability.